Homepage ➵ Free Connecticut 8379 Form

Free Connecticut 8379 Form

Edit Form Online
Structure

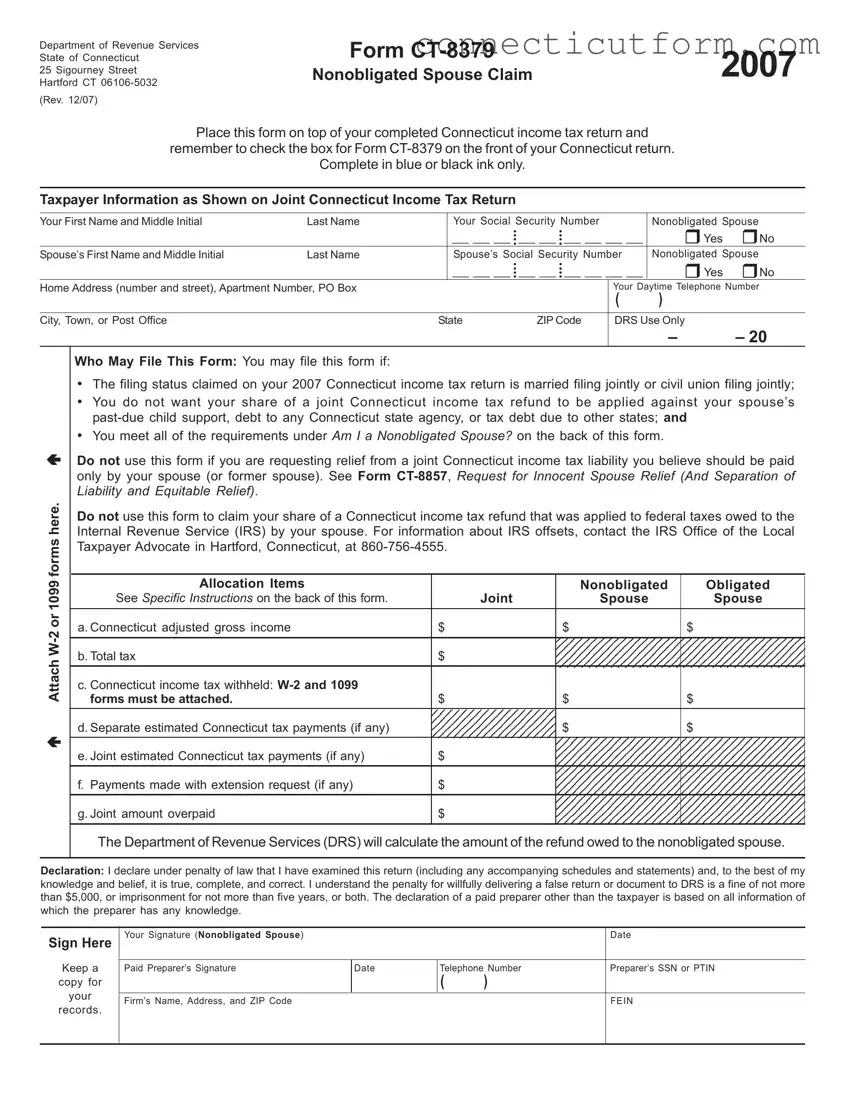
The Connecticut 8379 form serves as a critical resource for married or civil union partners who file their income tax returns jointly but do not want their share of the refund to be used for the spouse’s past-due debts, such as child support, debts to the state of Connecticut, or tax debts to other states. This form, formally titled the "Nonobligated Spouse Claim," requires detailed taxpayer information and demands precise documentation concerning income, tax withheld, and payments made, enabling the Department of Revenue Services (DR seniors) to accurately distinguish the nonobligated spouse’s tax obligations from those of their partner. The form outlines specific instructions on how to allocate income and payments between the spouses, providing a clear pathway for those who are not responsible for their spouse’s debts to claim their rightful share of the tax refund. Additionally, by including categories for allocation items and requiring declarations and signatures, the form ensures transparency and accountability in the filing process. The State of Connecticut has made provisions through Form CT-8379 for those seeking relief from their spouse’s financial liabilities, establishing a solid framework that recognizes the individual tax rights and responsibilities within a jointly filed return.
Connecticut 8379 Sample

Form CT-8379
Nonobligated Spouse Claim
Department of Revenue Services
State of Connecticut
(Rev. 12/25)
You may le this form if:
• Thelingstatusclaimedonyour2025Connecticutincometaxreturnismarriedlingjointly;
• YoudonotwantyourshareofajointConnecticutincometaxrefundtobeappliedagainstyourspouse’spast-due
childsupport,adebttoanyConnecticutstateagency,ortaxdebtduetoanotherstateortheInternalRevenue
Service(IRS);and
• YoumeetalloftherequirementsunderAm I a Nonobligated Spouse?onthebackofthisform.
Do notusethisformifyouarerequestingrelieffromajointConnecticutincometaxliabilityyoubelieveshouldbepaid
onlybyyourspouse(orformerspouse).SeeForm CT-8857,Request for Innocent Spouse Relief (And Separation of
Liability and Equitable Relief).
Do notusethisformtoclaimyourshareofaConnecticutincometaxrefundthatwasappliedagainstyourspouse’s
federalincometaxliability.ForinformationaboutIRSo󰀨sets,contacttheIRSatthetelephonenumberlistedonthe
NoticeofRefundO󰀨setissuedtoyou.
2025
Yoursignature(nonobligatedspouse) Date
Paidpreparer’ssignature Date Telephonenumber Preparer’sPTIN
Firm’sname,address,andZIPcode FEIN
Sign Here
Keep a
copyfor
your
records.
Declaration:IdeclareunderpenaltyoflawthatIhaveexaminedthisreturn(includinganyaccompanyingschedulesandstatements)and,tothebestof
myknowledgeandbelief,itistrue,complete,andcorrect.IunderstandthepenaltyforwillfullydeliveringafalsereturnordocumenttoDRSisaneofnot
morethan$5,000,imprisonmentfornotmorethanveyears,orboth.Thedeclarationofapaidpreparerotherthanthetaxpayerisbasedonallinformation
ofwhichthepreparerhasanyknowledge.
Attach ALL Forms W-2/1099
and Schedules CT K-1 here.
Yourrstnameandmiddleinitial Lastname
Spouse’srstnameandmiddleinitial Lastname
Taxpayer Information as Shown on Joint Connecticut Income Tax Return
Mailingaddress(numberandstreet),apartmentnumber,POBox
City,town,orposto󰀩ce State ZIPcode
Yourdaytimetelephonenumber
YourSocialSecurityNumber
Spouse’sSocialSecurityNumber
Nonobligatedspouse
Nonobligatedspouse
 
Yes No
 
Yes No
__ __ __ __ __ __ __ __ __
•
•
•
•
•
•
•
•
__ __ __ __ __ __ __ __ __
•
•
•
•
•
•
•
•
PlacethisformontopofyourcompletedConnecticutincometaxretu
rnandchecktheboxforFormCT-8379onthefrontofyourreturn.
Completeinblueorblackinkonly.Pleasenotethateachformisyearspecic.Topreventanydelayinprocessingyourreturn,thecorrectyear’s
form mustbesubmittedtotheDepartmentofRevenu
e Services (DRS).
Attach ALL Forms W-2/1099 and Schedules CT K-1.
Allocation Items
See Specic Instructions onthebackofthisform. Joint
Nonobligated
Spouse
Obligated
Spouse
a.Connecticutadjustedgrossincome $ $ $
b.Totaltax $
c.Connecticutincometaxwithheld:ALL Forms W-2/1099
must be attached. $ $ $
d.SeparateestimatedConnecticutincometaxpaymentsor
paymentsmadewithextensionrequest $ $
e.JointestimatedConnecticutincometaxpaymentsor
paymentsmadewithextensionrequest $
f. Connecticutearnedincometaxcredit $
g.Pass-throughentitytaxcredit:ALL Schedules CT K-1
must be attached. $ $ $
h.Jointamountoverpaid $
DRSwillcalculatetheamountoftherefundowedtothenonobligatedspouse.
– –
– –
Visit us at portal.ct.gov/DRS for more information.
FormCT-8379Back(Rev.12/25)
Form CT-8379 Instructions
Purpose: Use Form CT-8379,Nonobligated Spouse Claim,if:
• Youareanonobligatedspouseandallorpartofyouroverpayment
was(orisexpectedtobe)appliedagainst:
• Yourspouse’spastdueStateofConnecticutdebt(suchas
childsupport,studentloan,oranydebttoanyConnecticut
stateagency);or
• Yourspouse’staxdebtowedtoanotherstateortheIRS;and
• Youwantyourshareofthejointoverpaymentrefundedtoyou.
General Instructions
Am I a Nonobligated Spouse?
You area nonobligated spouse, if you meet all of the following
requirements:
• You led a joint Connecticut income tax return reporting an
overpaymentofincometax,allorpartofwhichwasorisexpected
to be applied against past-due child support, a debt to any
Connecticutstateagency,orataxdebtowedtoanotherstateor
theIRSbyyourspouse(theobligatedspouse);
• Youreceivedincome(suchaswages,interest,etc.)reportedon
thejointreturn;and
• YoumadeConnecticutincometaxpayments(suchaswithholding,
estimatedtaxpayments,orpaymentswithanextension)reported
onthejointreturnorqualifyfortheConnecticutearnedincome
taxcreditorhaveapass-throughentitytaxcredit.
Filing the Return: File Form CT-8379 with Form CT-1040,
Connecticut Resident Income Tax Return,Form CT-1040NR/PY,
Connecticut Nonresident or Part-Year Resident Income Tax Return,
or Form CT-1040X,Amended Income Tax Return for Individuals.
Electronic filers: If you are filing electronically, select the
indicator for Form CT-8379 on your Connecticut income tax
return.CompleteFormCT-8379anduploadasanattachment.
Paper filers:ChecktheboxforFormCT-8379onthefrontof
yourConnecticutincometaxreturn.Placethisformontopof
thecompletedConnecticutincometaxreturn.
Ifyoupreviouslyfiledyour2025Connecticutincometaxreturn
andyourrefundwasoffset,donotfileFormCT-1040X. Mail
FormCT-8379separatelyto:
Department of Revenue Services
POBox5035
HartfordCT06102-5035
Attach copies of ALL Forms W-2, 1099 and Schedules
CT K-1 to support income, withholding and any
pass-through entity tax credit claimed on Form CT-8379.
Specic Instructions
Taxpayer Information: Enterthetaxpayerinformationexactlyas
itappearsonyourConnecticutincometaxreturn.Thenameand
SocialSecurityNumber(SSN)enteredrstonthejointtaxreturn
mustalsobeenteredrstonFormCT-8379.
Allocation Items
a. Connecticut adjusted gross income:Enterthejointamount
asreportedonyourjointConnecticutincometaxreturn(Form
CT-1040,Line5;FormCT-1040NR/PY,Line5;orFormCT-1040X,
ColumnC,Line5).Thenseparatelyallocatetheindividualincomes
accordingtowhichspouseearnedtheincome.Thesumofthese
mustequaltheamountreportedasjointincome.
Nonresidents and Part-Year Residents only-Completethe
chartbelow.EnterthejointamountofyourConnecticut-sourced
income as reported on your Form CT-1040NR/PY,Line 6,
or Form CT-1040X, Column C, Line 6. Separately allocate
the Connecticut-sourced income between the two spouses.
The sum of these must equal the amount reported as joint
Connecticut-sourcedincome.
Joint $ .00
Nonobligated Spouse
$ .00
Obligated Spouse $ .00
Connecticut-Sourced Income
(Form CT-1040NR/PY, Line 6, or
Form CT-1040X, Column C, Line 6)
Nonresidents
and Part-Year
Residents Only
b. Total tax:EnterthejointConnecticuttaxliabilityasreportedon
yourjointConnecticutincometaxreturn(FormCT-1040,Line16;
FormCT-1040NR/PY,Line18;orFormCT-1040X,ColumnC,
Line20).
c. Connecticut income tax withheld:EnterthejointConnecticut
withholdingas reported on your jointConnecticut incometax
return(FormCT-1040,Line18;FormCT-1040NR/PY,Line20;or
FormCT-1040X,ColumnC,Line21).Listeachspouse’sshare
separatelyasshownonyourindividualwithholdingforms(such
asW-2sor1099s). Attach ALL Forms W-2/1099.
d. Separate estimated Connecticut income tax payments or
payments made with extension request:Enteranyseparately
paidestimatedConnecticutincometaxpaymentsorpayments
paidwithrequestforextension,intheappropriatespaces.
e. Joint estimated Connecticut income tax payments or
payments made with extension requests: Enter the
total amount of any joint estimated Connecticut income tax
paymentsorpaymentsmadewithrequestforextension.Include
overpaymentsappliedfromthepreviousyeariflingjointlywith
the same spouse.
f. Connecticut earned income tax credit: Enter the amount
reported on your joint Connecticut income tax return (Form
CT-1040,Line20a.;FormCT-1040X,ColumnC,Line22a).
g. Pass-through entity tax credit: Enter the amount reported
on your joint Connecticut income tax return (Form CT-1040,
Line 20c.; Form CT-1040NR/PY, Line 22b.; Form CT-1040X,
ColumnC,Line22c).Listeachspouse’sshareofpass-through
entitytaxcreditseparately.Attach ALL Schedules CT K-1.
h. Joint amount overpaid: Enter the joint amount overpaid as
reported on your joint Connecticut income tax return (Form
CT-1040, Line 22; Form CT-1040NR/PY, Line 24; or Form
CT-1040X,ColumnC,Line27).
Nonobligated Spouse Refund: DRS will calculate the amount
of thenonobligated spouse’s refund. The nonobligatedspouse’s
shareofthejointConnecticuttaxoverpaymentcannotexceedthe
jointoverpayment.
Signature: The nonobligated spouse must sign this form.
Others Who May Sign for the Nonobligated Spouse:Anyone
withasignedLGL-001,Power of Attorney,maysignonbehalfof
thenonobligatedspouse.AttachacopyoftheLGL-001.
Paid Preparer’s Signature: Anyoneyoupaytoprepareyourreturn
mustsignanddateit.PaidpreparersmustalsoentertheirPersonal
TaxIdenticationNumber(PTIN),andtheirrm’sFederalEmployer
IdenticationNumber(FEIN)inthespacesprovided.

Document Features

Fact Details
Purpose Form CT-8379, Nonobligated Spouse Claim, is used by individuals who do not want their share of a joint Connecticut income tax refund to be applied against their spouse’s past-due child support, state agency debt, or other states’ tax debts.
Eligibility To be eligible, individuals must file jointly and meet certain conditions, such as not owing any past-due child support or agency debts themselves, and part of their joint tax refund is expected to be applied to the spouse's debts.
Required Attachments All forms W-2 and 1099 showing Connecticut income tax withheld must be attached to Form CT-8379 for processing.
Governing Law Form CT-8379 is governed by Connecticut state law, specifically addressing the tax filing and refund processes for married or civil union couples filing jointly in the state of Connecticut.

How to Use Connecticut 8379

Filing Form CT-8379 is crucial when you don't want your share of a Connecticut income tax refund to be used for your spouse's past debts, such as child support or state-owed obligations. Carefully completing this form ensures that your portion of any refund is protected. Below, find a step-by-step guide that will help you fill out the form accurately and efficiently.

  1. Start with your Taxpayer Information. Enter your first name, middle initial, last name, and Social Security Number exactly as they appear on your joint Connecticut income tax return.
  2. Move next to the Nonobligated Spouse section. Answer whether you are the nonobligated spouse by checking "Yes" or "No".
  3. Continue by filling out the corresponding information for Spouse's First Name and Middle Initial, Last Name, and Spouse's Social Security Number.
  4. Provide your Home Address (number and street), Apartment Number, PO Box, followed by your Daytime Telephone Number, then the City, Town, or Post Office, State, and ZIP Code.
  5. For the Allocation Items section, start with (a.) Connecticut adjusted gross income. Enter the joint amount and then allocate the amounts to the nonobligated and obligated spouse columns as appropriate.
  6. For (b.) Total tax, note the joint Connecticut tax liability and do the same allocation.
  7. Under (c.) Connecticut income tax withheld, attach W-2 or 1099 forms and allocate the withheld income tax between both spouses accordingly.
  8. For (d.) Separate estimated Connecticut tax payments, and (e.) Joint estimated Connecticut tax payments, list any payments made individually or jointly. Do the same for (f.) Payments made with an extension request.
  9. Enter the (g.) Joint amount overpaid as reported on your Connecticut income tax return, again splitting between spouses as applicable.
  10. Under Declaration, read the statement carefully. The form must be signed by the nonobligated spouse, attesting to the accuracy of the information provided.
  11. Ensure the nonobligated spouse signs and dates the form. If a paid preparer completed the form on your behalf, they must also sign, provide their telephone number, SSN or PTIN, and include their firm’s name, address, and FEIN.

Finishing this process correctly is paramount. Once completed, remember to place the form on top of your Connecticut income tax return, marking the appropriate box for Form CT-8379 on the front of your return. If your Connecticut income tax return was already filed, you'll need to send Form CT-8379 separately to the specified address. This detailed completion will ensure your rights are preserved and that only your spouse's share of the refund is available for debt offset.

More About Connecticut 8379

  1. Who should file Form CT-8379 in Connecticut?

    If you're married or in a civil union and file jointly in Connecticut, but don't want your portion of a state income tax refund to be used for your spouse's debts like past-due child support, state agency debts, or tax debts to other states, Form CT-8379 is for you. It's not for those seeking relief from joint tax liabilities or whose refund was taken for federal IRS debts.

  2. What requirements must I meet to be considered a nonobligated spouse?

    To qualify, you must have filed a joint tax return where only your spouse has past-due debts as described, you must have reported income on this return, contributed to the tax payments, not owe any such debts yourself, and an overpayment was or is expected to be applied to these debts.

  3. How do I file Form CT-8379?

    Place Form CT-8379 on top of your Connecticut tax return when filing. If you already filed your return, you can send Form CT-8379 separately to the Department of Revenue Services. Ensure to check the box for Form CT-8379 on your tax return and attach any W-2 or 1099 forms showing Connecticut tax withheld.

  4. What information do I need to provide on Form CT-8379?

    Provide details as they appear on your joint income tax return, allocate your and your spouse's portions of income, tax liabilities, withholdings, estimated payments, and overpayments accordingly. Attach your W-2 or 1099 forms as well.

  5. How is the refund calculated for a nonobligated spouse?

    The Connecticut Department of Revenue Services will calculate your refund based on the portion of the overpayment that is attributable to you, not exceeding the total joint overpayment amount.

  6. What happens if I filled out the form incorrectly?

    If errors are found, it could delay processing. Ensure all information matches what was submitted on your joint tax return and verify that your calculations are correct.

  7. Can I file Form CT-8379 electronically?

    As of the last update, you must submit this form in paper form along with your tax return. If filed after the fact, mail it directly to the specified address of the Department of Revenue Services.

  8. What should I do if I don't agree with the debt claimed by my spouse?

    Form CT-8379 isn't for disputing the validity of the debt. If you disagree with the debt itself, contact the agency to which the debt is owed. For disagreements on the tax burden allocation, consider Form CT-8857 for Innocent Spouse Relief.

  9. Who can sign Form CT-8379 on behalf of the nonobligated spouse?

    The nonobligated spouse must sign the form. If they are unable to, a representative holding Power of Attorney may sign, but a copy of the Power of Attorney must be attached. Paid preparers must also sign, date, and provide their identification numbers.

Common mistakes

Filling out the Connecticut Form CT-8379, the Nonobligated Spouse Claim, can be a tricky process filled with potential pitfalls. Designed for spouses seeking their share of a joint tax refund that might otherwise be applied to the other spouse's debts, such as back taxes, child support, or state agency debts, it's essential to get it right. Here are seven common mistakes people make:

  1. Not verifying the taxpayer information. It's fundamental yet often overlooked. The information entered in the taxpayer section must exactly match that on the Connecticut income tax return. Similar discrepancies can cause delays or even rejection.
  2. Failing to check the box for Form CT-8379 on the front of the Connecticut income tax return. This could result in the form being overlooked and not processed alongside the tax return.
  3. Improper documentation attachment. Not attaching, or incorrectly attaching, copies of all W-2 and 1099 forms showing Connecticut income tax withheld is a common mistake. These forms are crucial for verifying withheld tax amounts allocated to each spouse.
  4. Incorrect allocation of income and taxes. The division of Connecticut adjusted gross income, total tax, withholdings, and estimated payments between spouses must be accurately reported. Miscalculations or failing to report these allocations accurately can affect the nonobligated spouse's refund amount.
  5. Not including joint estimated Connecticut tax payments. Omitting these payments can lead to an underestimation of the refund due to the nonobligated spouse.
  6. Forgetting to sign the form. The nonobligated spouse's signature is mandatory for processing. If the form is unsigned, it will not be processed, delaying any potential refunds.
  7. Overlooking the need for a Power of Attorney signature when applicable. If someone other than the nonobligated spouse is submitting the form on their behalf, a copy of the Power of Attorney must be attached.

Avoiding these mistakes is key to ensuring that the process of claiming a rightful share of a joint tax refund goes smoothly. It's not just about filling in the blanks; it's about paying close attention to detail, understanding each section, and providing accurate and complete information. This helps ensure that the Department of Revenue Services can process the form efficiently, leading to a quicker resolution and refund payment. Whether you're dealing with withheld wages, student loan debts, or other financial binds connected to your spouse, Form CT-8379 is a critical tool in preserving your financial rights.

In conclusion, properly completing Form CT-8379 demands thoroughness, accuracy, and an understanding of its requirements. By avoiding these common mistakes, filers can better navigate the complexities of tax filings, ensuring that both parties' financial interests are properly represented and protected.

Documents used along the form

When navigating the complexities of tax claims in Connecticut, especially involving situations like the nonobligated spouse claim, a variety of forms and documents alongside Form CT-8379 can play crucial roles. Understanding these additional forms helps ensure taxpayers are well-prepared and can secure their rightful claims effectively.

  • Form CT-1040: The primary individual Connecticut income tax return form for residents, necessary for reporting annual income, tax deductions, and credits.
  • Form CT-1040EZ: A simplified version of the Connecticut income tax return for individuals with straightforward tax situations, emphasizing efficiency.
  • Form CT-1040NR/PY: Tailored for non-residents or part-year residents of Connecticut, this form accommodates those who need to report income generated within the state.
  • Form CT-1040X: Used for amending previously filed Connecticut income tax returns, allowing taxpayers to correct errors or claim a more favorable tax status.
  • Form W-2: A crucial wage and tax statement provided by employers, detailing an employee's annual earnings and the amount of taxes withheld.
  • Form 1099: A series of documents reporting various types of non-employment income, such as dividends, interest, and freelance income, necessary for accurate tax filing.
  • Form CT-8857: Request for Innocent Spouse Relief form, offering a route for those seeking relief from joint tax liabilities under certain conditions.
  • Form CT-2210: Underpayment of Estimated Tax by Individuals, Estates, and Trusts form, used when taxpayers owe penalties for not meeting estimated tax payment requirements.
  • Form CT-4868: Application for Extension of Time to File Connecticut Income Tax Return for Individuals, allowing taxpayers extra time to file their return without penalty for late submission.
  • Power of Attorney and Declaration of Representative (Form LGL-001): Legal documentation authorizing another person to make decisions and handle tax matters on one’s behalf.

Together, these forms and documents encompass the breadth of resources available to taxpayers in Connecticut, particularly when dealing with the allocation of tax liabilities and refunds between spouses. Accurate and informed use of each can greatly impact the efficiency and success of navigating tax obligations and protecting individual rights within the tax system.

Similar forms

The Connecticut 8379 form is similar to other forms designed to offer relief or assert rights under specific tax filing statuses. These documents help taxpayers navigate their obligations in scenarios that require a detailed declaration of individual finances and liabilities, often involving joint filings with a spouse. Each form, while unique in its purpose and application, shares commonalities with the Connecticut 8379 form in terms of providing protections or remediation for taxpayers under specific circumstances.

One such document is the IRS Form 8379, Injured Spouse Allocation. This form serves a similar purpose at the federal level to what Connecticut’s Form 8379 accomplishes at the state level. It is designed for taxpayers who do not wish for their portion of a joint tax refund to be applied to their spouse’s past due federal debts, such as federal taxes, child or spousal support, and federal non-tax debts, like student loans. Both forms require details on income, tax payments, and withheld amounts, allocated between the spouses, to properly calculate the non-obligated party’s share of the overpayment. They also share a fundamental goal: to protect the financial interests of a spouse who is not responsible for the other’s debts.

Another related document is Form CT-8857, Request for Innocent Spouse Relief (And Separation of Liability and Equitable Relief). Though it serves a markedly different function, it bears relevance through its connection to tax liabilities arising from joint filings. While the CT-8379 form focuses on refund allocations and not applying one spouse's refund to cover the debts of the other, Form CT-8857 allows a taxpayer to apply for relief from joint tax liabilities if it would be unfair to hold them responsible for the understatement or understatement of tax due to actions of their spouse or ex-spouse. This includes scenarios where one spouse may have erroneously reported income or claimed deductions. The underlying similarity is the recognition of individual rights within the joint filing context, and the legal mechanisms to protect those rights.

Each document underscores the complexities of tax law and the recognition of individual circumstances within the framework of joint financial responsibilities. They highlight the mechanisms available to taxpayers seeking to ensure fair treatment under the law, reflecting a nuanced understanding of personal and shared financial obligations.

Dos and Don'ts

When you're filling out the Connecticut 8379 form, there are specific dos and don'ts that can help ensure your form is processed smoothly and correctly. Below are important points to consider.

Things You Should Do
  • Ensure you write in blue or black ink to maintain the form's readability.
  • Place this form on top of your completed Connecticut income tax return and mark the checkbox for Form CT-8379 on the front of your Connecticut return to signal the attachment.
  • Attach copies of all forms W-2 and 1099 that show Connecticut income tax was withheld. This documentation is critical for verifying the information provided on your form.
  • Sign the form if you are the nonobligated spouse. A signature is required to validate the form, and if someone has a Power of Attorney, they may sign on your behalf, but remember to attach a copy of the Power of Attorney.
Things You Shouldn't Do
  • Do not use this form if you believe the tax liability should be solely your spouse's responsibility and are seeking relief for yourself. Instead, Form CT-8857, Request for Innocent Spouse Relief, would be the appropriate form.
  • Avoid using Form CT-8379 to claim a portion of a Connecticut income tax refund that was applied to federal taxes owed by your spouse to the IRS. This form is not applicable for federal tax offset disputes.
  • Do not omit your daytime telephone number. Providing this information can expedite the process should any issues or questions arise regarding your form.
  • Avoid submitting the form without checking that all taxpayer information matches exactly as shown on your Connecticut income tax return. Discrepancies can lead to processing delays.

Misconceptions

Understanding taxation and its related forms can be a real maze, especially when it comes to specific situations like filing Form CT-8379 in Connecticut. It's designed for a unique scenario - when one spouse does not want their joint tax refund applied to the other spouse's outstanding debts. Let's unravel some common misconceptions about this form to ensure you have all the facts straight.

  • Misconception 1: Form CT-8379 is for filing separate taxes. In reality, this form is specifically for married couples or those in a civil union who file jointly but want to protect one spouse's portion of a tax refund from being applied to the other's debts, such as past-due child support, state agency debts, or debts to other states.

  • Misconception 2: Any couple can file Form CT-8379. Only couples who filed jointly and where one spouse is not responsible for the other's specific debts can use this form. It's not a one-size-fits-all solution and requires meeting specific eligibility criteria.

  • Misconception 3: You can use Form CT-8379 to separate liabilities on other taxes. This form only applies to the Connecticut income tax overpayment and its potential refund. It doesn't separate liabilities for other taxes or ensure that future refunds are divided.

  • Misconception 4: Filing Form CT-8379 will delay your refund. While it's true that additional documentation and review might take time, the form itself is designed to ensure that the nonobligated spouse gets their fair share of the refund without undue delay attributable to the form's processing.

  • Misconception 5: Form CT-8379 is only for protecting refunds from child support claims. Although child support is a common debt that can claim a tax refund, this form also applies to debts owed to any Connecticut state agency or tax debts to other states.

  • Misconception 6: You don't need to attach income documentation. On the contrary, attaching forms W-2 and 1099 showing Connecticut income tax withheld is crucial for filing Form CT-8379. This documentation is necessary to calculate the nonobligated spouse's share of the refund accurately.

  • Misconception 7: The form can be used for federal tax issues. Form CT-8379 only deals with Connecticut state tax refunds. For federal tax issues or to protect a federal refund from being offset for a spouse's debts, other forms and procedures with the IRS are involved.

  • Misconception 8: The nonobligated spouse doesn't need to sign Form CT-8379. In fact, the form requires the signature of the nonobligated spouse to be valid. If the nonobligated spouse cannot sign, a Power of Attorney may do so, but proper documentation must be attached.

  • Misconception 9: Once you file Form CT-8379, you don't have to file it again for future tax years. Each tax year is separate, and if the same conditions apply, the form needs to be filed each year with the joint tax return to protect the nonobligated spouse's refund.

Understanding these points can clear up confusion and help ensure that couples in Connecticut navigate their tax responsibilities effectively, especially when it comes to managing individual liabilities and entitlements in a joint tax refund scenario.

Key takeaways

Understanding the Connecticut Form CT-8379 for Nonobligated Spouses is crucial for couples dealing with specific financial disputes. Here are seven key takeaways to guide individuals through this process:

  • Eligibility: The Form CT-8379 should only be used if you are married or in a civil union and filing jointly in Connecticut, you don't want your portion of a joint tax refund to be used for your spouse's obligations, and you meet the criteria for a nonobligated spouse.
  • Specific Use: This form is not applicable if seeking relief from joint tax liabilities or if your tax refund is being taken for federal debts to the IRS. It specifically addresses situations where a state debt or child support owed by your spouse could impact your joint state tax refund.
  • Attachment Requirements: When submitting Form CT-8379, all W-2 and 1099 forms showing Connecticut income tax withheld must be attached. This ensures that the Department of Revenue Services can accurately determine your share of the tax refund.
  • Filing Procedure: Form CT-8379 must be placed on top of your completed Connecticut income tax return with the designated box checked. If filing after the original return, it should be mailed to the specific address provided in the form instructions.
  • Income and Payments Allocation: The form requires detailed information about both spouses' income, tax withheld, estimated payments, and any payments made with an extension request. Accurate allocation is key to determining the nonobligated spouse's refund.
  • Nonobligated Spouse's Refund: The Department of Revenue Services (DRS) calculates the nonobligated spouse's refund based on the information provided. The refund to the nonobligated spouse cannot exceed the total joint overpayment reported on the tax return.
  • Signature Requirements: The nonobligated spouse must sign the form. If someone holds Power of Attorney for the nonobligated spouse, they can sign on their behalf, provided a copy of the Power of Attorney is attached. Paid preparers must also sign and provide their identification numbers.

By adhering to these guidelines, nonobligated spouses can navigate the complexities of safeguarding their portion of a joint tax refund in Connecticut.

Please rate Free Connecticut 8379 Form Form
4.69
Exemplary
320 Votes